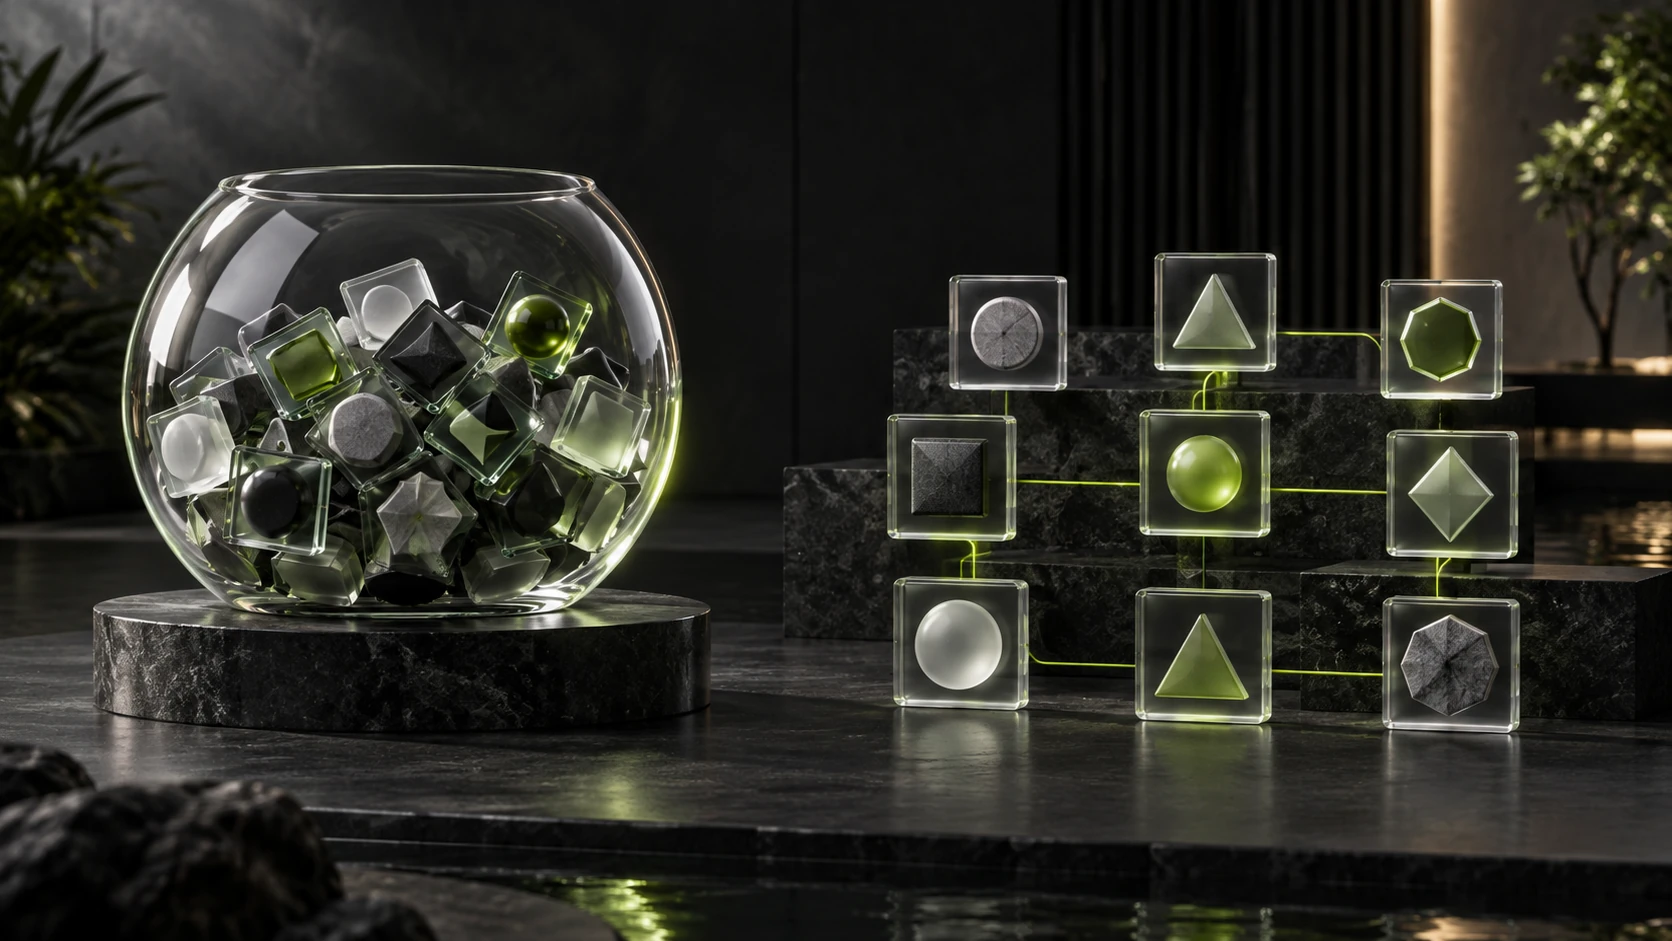
Glass bowl of pooled investment tiles beside a grid of individually held tiles connected by a green line.
Blog

Halal Mutual Funds vs Custom Indexing: What Changes When You Own the Stocks

A fair comparison of halal mutual funds and custom indexing, covering ownership, screening, portfolio control, total costs, taxes, and investment risk.
September 28, 2026
1-Min Summary

By Tarif Homsi, Founder & CEO

Short answer: A halal mutual fund pools investors' money in a portfolio run under the fund's disclosed strategy. With custom indexing, an investor owns a portfolio of individual securities selected and managed under a defined screening process. The first approach is simpler to hold; the second can allow more control over exclusions and tax lots. Neither structure is automatically Shariah-compliant, cheaper, better diversified, or more likely to outperform.

The useful comparison is not a contest between a fund ticker and an adviser slogan. Ask what you actually own, who screens it, how often holdings are checked, what the full costs are, and whether customization or taxable-account flexibility has value in your circumstances. NoorVest offers custom indexing, so we have an obvious commercial interest in this comparison. We have included the fund's genuine advantages and the limits of our approach.

  • Fund shares give exposure to a pooled portfolio; custom indexing puts the selected securities in your own account.
  • Review the specific Shariah methodology, oversight, purification process, and portfolio holdings in either approach.
  • Compare total costs and investment risks before giving weight to possible tax advantages.

What do you own in each approach?

When you buy a mutual fund, you own shares of the fund. The fund owns its underlying investments and its manager makes portfolio decisions under a prospectus. You can usually buy or redeem fund shares at the next calculated net asset value on a business day, subject to the fund's terms. A fund can be actively managed or designed to follow an index. The words “mutual fund” do not tell you which one it is. The SEC's investor bulletin explains the pooled structure and pricing.

Custom indexing starts with a target market exposure, then holds selected individual securities in the client's managed account. The adviser may omit companies that fail its Shariah screen or a client's additional restrictions. It may hold a representative subset rather than every company in the reference index. The client can see the positions and their tax lots, but the holdings still need ongoing professional oversight. FINRA's explanation of direct indexing describes both the control and the risk of diverging from an index.

Halal mutual funds and custom indexing: structural differences
QuestionHalal mutual fundCustom indexing account
What is held?Shares of a pooled fundSelected individual securities in the client's account
Who chooses holdings?The fund manager, within its disclosed mandateThe adviser under the account's methodology and client instructions
Can you exclude one company?Generally not inside the fundOften possible, subject to portfolio constraints and suitability
How is it priced?Typically at the next calculated net asset valueEach security trades at its market price
Where are the fees?Fund expense ratio and any applicable sales, account, or adviser chargesAdvisory and account charges, plus any trading or custody costs
Who controls taxable lots?The investor controls sales of fund shares, not the fund's underlying lotsIndividual security lots can be managed, subject to tax and trading limits

This table describes the structures, not every product. A mutual fund's share class, investment style, distribution policy and fees can vary. A custom indexing account's holdings, trading authority, and restrictions depend on the advisory agreement. Read the documents for the particular arrangement.

How do you check Shariah compliance?

A halal label does not settle the question. For a mutual fund, start with the prospectus, current holdings, screening methodology, Shariah board or adviser, and the fund's treatment of cash and incidental non-compliant income. Check whether its mandate permits derivatives, borrowing or securities lending, and whether the Shariah review covers those practices as well as the holdings. Ask how often the manager rescreens and what happens when a holding stops qualifying. Review the purification policy and whether it provides a usable figure to investors. Investor.gov recommends reading the prospectus before investing, especially the strategy, risks, fees and tax sections.

A custom portfolio needs the same discipline at the security level. NoorVest's published AAOIFI-aligned methodology first excludes prohibited core business activities. For otherwise eligible companies it uses three screens: interest-based debt divided by market capitalization below 30%; interest-earning deposits or securities divided by market capitalization below 30%; and prohibited-activity income divided by total income below 5%. MuslimXchange reviews listed securities quarterly. NoorVest reports applicable purification information annually. These are the rules for NoorVest's process, not thresholds we can attribute to every halal mutual fund.

Fund and adviser screens may use different denominators, revenue classifications, timing, or Shariah opinions. That can produce different answers for the same company without proving that one provider is careless. The documents should tell you which standard is followed and who is accountable for decisions. See our AAOIFI standards guide for the distinction between a published standard, an aligned screening method and a product-specific review.

Purification is also separate from Zakat. A fund may publish a purification factor; Saturna's Amana tools are one public example of fund-specific reporting and explicitly distinguish the two. NoorVest's annual reporting follows its own documented process. Neither approach turns an otherwise prohibited core business into a permissible investment by donating part of the income. Our Zakat on stocks and investments guide treats the separate wealth-obligation question.

What can you change after investing?

A pooled fund can be an efficient way to obtain a professionally managed screened portfolio with one transaction. The trade-off is that an individual shareholder normally cannot ask the manager to remove one company from the common portfolio. If a fund's Shariah interpretation or sector mix no longer suits you, changing your own fund position may be the only practical response. That can have costs or tax consequences.

In a managed account, restrictions can be applied to the individual securities. NoorVest describes its Halal Custom Indexing process as choosing target market exposure, screening an investable universe, then managing a personalized portfolio for additional security restrictions and tax considerations. This flexibility is useful when a client has an employer-stock position, legacy holdings, or an additional values-based exclusion. It also creates a management problem: every exclusion reduces the investable set and may change sector weights, concentration and returns relative to the chosen benchmark.

Custom indexing does not make an unscreened conventional index halal by changing its name. The actual securities and the trading arrangement must satisfy the applicable methodology. NoorVest's platform-level Shariah pronouncement has a defined scope; it does not certify a third-party fund or guarantee that any future holding will always pass screening. Our halal stock investing guide explains the security-by-security review.

How should you compare the full cost?

Start with the work you want done, then price that work. A mutual fund's expense ratio is deducted from fund assets, so it reduces your return even though it does not appear as a separate bill. A particular share class may also have a sales load or other charges. If you hold the fund through an adviser, an advisory fee can sit on top. The SEC's fee bulletin explains why the share class and all account-level charges matter.

Custom indexing avoids a fund expense ratio on the individually held stocks, but it is not free. An adviser may charge a percentage of assets or a fixed amount; brokerage, custody, trading, transition and tax-related costs may also matter. NoorVest describes flat-fee plans. Compare the current written fee schedule and included services with the total cost of a fund route. A fund held without an adviser and a managed account that includes planning are not the same service, so a headline percentage comparison alone is misleading.

Ask what happens as the account grows or shrinks, whether a fund fee is added if other assets are used, and who pays for advice outside portfolio management. A lower stated fee does not guarantee a better result. Costs, diversification, strategy differences, taxes and investor behavior all affect the eventual outcome.

Does owning the stocks improve the tax picture?

Potentially, in a taxable account, but the advantage depends on the investor. A mutual fund investor can choose when to sell fund shares, subject to the fund's terms. The investor generally cannot choose which of the fund's underlying positions the manager sells. Capital-gain distributions can arise from the fund's own activity even when a shareholder has not sold their shares. The SEC explains the different tax mechanics of pooled funds.

With individual securities, an adviser can review each position and tax lot. It may be possible to realize a loss in one holding while leaving other positions invested. This is a tool, not a promised tax saving. A loss may not exist when you need one; realizing one can change exposure; future gains may offset an earlier benefit; and extra trades can create costs. The IRS wash-sale rules can disallow a loss when substantially identical securities are acquired within the relevant 30-day window before or after a loss sale. The facts of each transaction matter, including purchases in other accounts. A qualified tax professional should assess a proposed strategy.

Tax-loss harvesting has much less relevance inside a tax-advantaged retirement account, where trades generally do not create current capital gains or losses in the same way as a taxable brokerage account. An investor comparing a mutual fund in an IRA with a custom taxable account is comparing different tax wrappers as well as different portfolio structures. Keep those questions separate. If an adviser claims that custom indexing will always produce “tax alpha,” ask for the assumptions and the risks behind the claim.

Where can each approach disappoint?

A screened mutual fund may hold fewer sectors or companies than a conventional broad-market fund. Its manager can make decisions you would not make yourself, and its portfolio can change between reports. If it is active, it may diverge from an index by design. If it follows an index, its return can still differ because of fees, trading and screening. Fund diversification can reduce dependence on a single company, but it cannot prevent losses.

Custom indexing can make a client's restrictions explicit, but it may be harder to replicate a benchmark when many companies are excluded. A smaller account may hold a narrower sample. Rebalancing, company-level screening changes and tax trades can add turnover. FINRA cautions that direct-indexing results can differ markedly from the reference index and that fees may exceed those of a typical passive portfolio. Neither structure removes market risk or ensures a particular outcome.

Operational details deserve attention too. Ask who monitors holdings, how exceptions are handled, what report you receive, and how you can exit or transfer positions. With a mutual fund, read its redemption and share-class terms. With a managed account, read the advisory agreement and identify who has trading authority and custody. These are less glamorous questions than an expected return chart, but they determine what happens when circumstances change.

A practical way to make the comparison

  1. Define the job of the money. Is it long-term equity exposure, retirement savings, or money needed soon? Neither an equity fund nor an equity custom index is a substitute for cash required on short notice.
  2. Choose the account type. Taxable brokerage, IRA and employer plan access can change the value of customization and tax management.
  3. Compare actual screening documents. Identify the Shariah method, reviewer, holdings, rescreening frequency and purification process for each option.
  4. Test the exposure. Look at country, sector and company weights. Ask how exclusions or fund choices change concentration and benchmark tracking.
  5. Calculate all-in costs. Include the fund share class, adviser charges, account fees, trading costs and the services received. Use current documents, not a generic chart.
  6. Ask what you can control. If you need to restrict a holding, accommodate existing shares or set a gains budget, determine whether the arrangement actually permits it.
  7. Review the exit. How and when can you redeem a fund or transfer individual securities? What taxable gains, transaction charges or restrictions might arise?

The answer can also be “both” within a broader plan. A household may use a pooled investment for one account and a managed stock portfolio elsewhere, if each serves a distinct purpose and clears its own Shariah and suitability review. This article does not prescribe that allocation. For fund-versus-ETF questions, see our halal ETF due-diligence guide. For the broader index question, see Are Index Funds Halal?

Frequently asked questions

Are all mutual funds labeled Islamic Shariah-compliant?

A label alone cannot answer that. Read the fund's current prospectus, holdings, screening rules, Shariah oversight and purification policy. A qualified Shariah adviser can help assess the specific fund under the standard you follow.

Does custom indexing mean buying every stock in an index?

No. A strategy may hold a representative selection and exclude companies under its screening method or client restrictions. Those choices can change diversification and returns relative to the reference index.

Is custom indexing automatically cheaper than a halal mutual fund?

No. A managed account can have advisory and other costs even without a fund expense ratio on its individual stocks. Compare current all-in fees for equivalent services and account sizes. A low-cost fund held directly may cost less.

Does tax-loss harvesting guarantee a lower tax bill?

No. Benefits depend on taxable gains, future transactions, tax rates and the rules that apply to each trade. A wash sale may disallow a loss. The strategy can also change portfolio exposure and incur costs. Consult a qualified tax professional before relying on an expected benefit.

Can a halal mutual fund be more diversified?

Yes. A particular fund may hold more eligible companies or markets than a smaller customized account. The reverse can also be true for another pair of portfolios. Compare actual holdings and weights, not the label of the structure.

Why is NoorVest comparing funds with its own service?

NoorVest offers custom indexing, so it has a commercial interest in explaining that approach. A fund can be a reasonable, simpler choice for some investors. The right comparison uses current documents, full costs, Shariah governance and the investor's circumstances, not an assumed winner.

Where NoorVest fits

NoorVest's custom indexing process screens individual securities and manages a portfolio around the client's objectives and permitted restrictions. Its Shariah compliance page documents the platform review, screening responsibilities and monitoring schedule. Its financial planning service considers the portfolio in the context of the client's broader finances. An introductory conversation can clarify whether the service addresses a real need; it does not obligate you to replace a fund that is already working for you. Talk with NoorVest if you want to review the trade-offs.

Important disclosure

This article is educational and may be considered an advertisement for NoorVest's advisory services. NoorVest offers custom indexing and therefore has a commercial interest in the comparison. Nothing here is a religious ruling, certification of a third-party fund, personalized investment recommendation, tax advice or guarantee of results. Securities can lose value, and Shariah screening can reduce the investable universe and increase concentration or tracking differences. Fund features and fees vary by prospectus and share class. Custom indexing costs, restrictions and account eligibility vary by agreement. Tax outcomes depend on individual facts and applicable law. Read current documents and consult qualified investment, Shariah and tax professionals where appropriate.

About the author

Tarif Homsi is NoorVest's founder and CEO. His work focuses on bringing financial planning and Shariah-conscious portfolio management together for U.S. Muslim investors. Sources reviewed September 25, 2026.

Primary sources and further reading

Get Free Consultation
Light Mode
Toggle cloudsstars