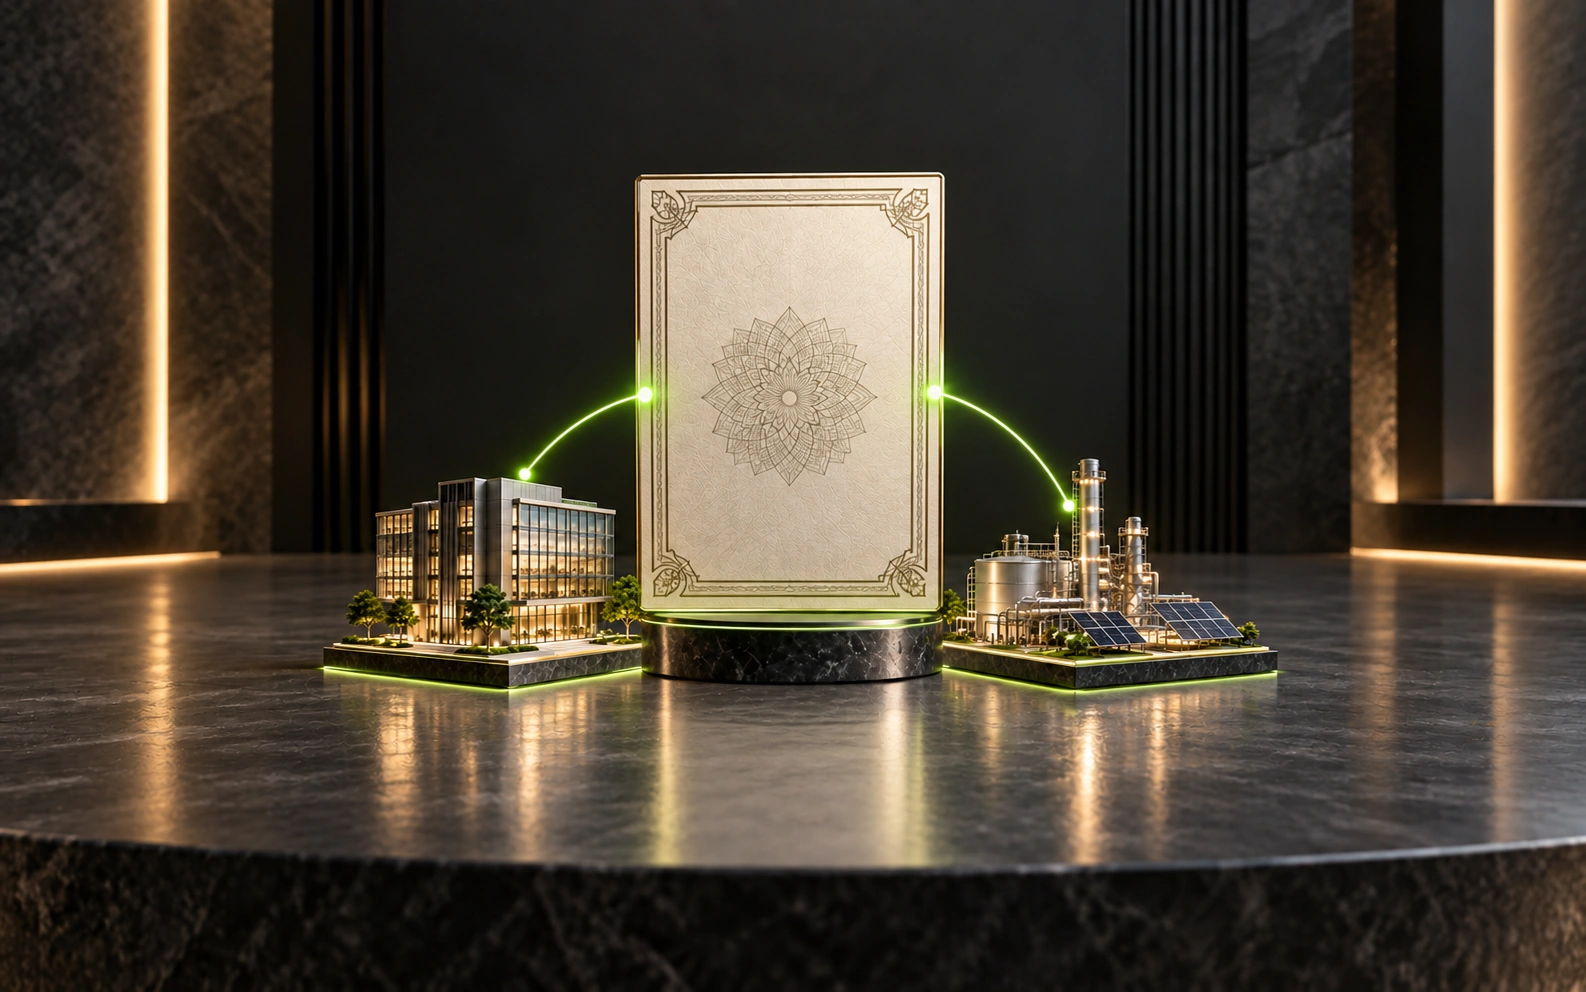
An investment certificate linked to a commercial building and infrastructure assets, illustrating Sukuk ownership and cash flows.
Blog

Sukuk Explained: A Practical Guide to Islamic Bonds

Understand Sukuk Islamic bonds, asset-based versus asset-backed structures, payments, investment risks, Shariah review and ways U.S. investors can research access.
October 2, 2026
1-Min Summary

Written by Tarif Homsi, Founder & CEO

Short answer: Sukuk are investment certificates structured around specified assets, their use, or an investment activity. Often called “Islamic bonds,” they aim to provide returns through Shariah-compliant transactions rather than interest on a conventional loan. What investors own, how they are paid, and what they can recover in a default depend on the particular documents.

A building shown in a brochure is not proof that investors can seize it. A scheduled distribution is not a guarantee. Before buying an individual issue or a sukuk fund, examine the contracts, payment source, legal recourse, Shariah review, costs and liquidity. This guide explains those questions without approving a particular security or recommending a portfolio allocation.

  • Distinguish the religious framework from enforceable investor rights.
  • Separate an individual sukuk's maturity from the life of a fund holding many issues.
  • Assess possible loss alongside the prospect of income.

What are sukuk, and why are they called Islamic bonds?

“Sukuk” is the plural of sakk, commonly translated as a certificate. AAOIFI Shariah Standard No. 17 describes investment sukuk as equal-value certificates representing shared ownership in assets, rights to use assets, services, or specified investment activity once the subscription proceeds have been deployed. The standard distinguishes them from conventional bonds and company shares.

The bond comparison is useful because an issue may raise capital, make periodic payments and have a scheduled maturity. But it is shorthand, not a complete legal description. A conventional bond creates a creditor's claim under a debt agreement; a sukuk's contractual basis may instead involve a lease, partnership or investment agency. Neither the Arabic name nor a similar payment schedule settles the Shariah question.

For the wider context, our Islamic finance in the USA guide separates household financing, investing and banking. Our riba guide explains why a return from genuine trade or ownership is not automatically the same as a stipulated increase on a loan.

How can a sukuk transaction work?

Consider a simplified, hypothetical lease arrangement—not an actual offering. Investors subscribe for certificates issued through a special-purpose vehicle, a separate entity used to carry out the transaction. Their funds acquire the specified asset interest. The asset is leased to an operating business, and collected rent helps fund investor distributions after agreed expenses. A separate agreement may govern the sale or transfer of that interest at the end of the term.

This example gives you a starting diagram: investors, issuing vehicle, asset and lessee. The next step is to test it against the documents. Was an asset interest actually transferred? What interest was it? Who pays if rent is late? Who handles damage and ownership expenses? Does a purchase undertaking require another party to buy the interest later, and can that undertaking be enforced?

If the operating business cannot pay, the diagram alone does not answer what investors recover. Nor does the example describe every sukuk. Some issues use multiple contracts or a changing pool of assets. Ask the arranger to identify the relevant agreements and cash flows in writing, rather than relying on an illustration.

What are the main sukuk structures?

The following are reading categories, not product approvals. Nigeria's securities regulator provides an investor explanation of several sukuk contracts; its jurisdiction-specific rules should not be assumed to apply to a U.S. investment.

Ijarah: returns linked to a lease

An ijarah structure involves leased assets or rights to their use. Rent is central to the payment arrangement. Review the lease, ownership responsibilities and any end-of-term purchase mechanism together. A stated rental amount does not mean that every scheduled distribution will be made.

Musharakah and mudarabah: investment participation

Musharakah involves partnership participation. In mudarabah, capital providers and an investment manager have different roles. Read how profit is allocated and how losses, misconduct and contractual breaches are treated. Do not assume the manager guarantees the invested capital simply because a document sets out an expected return.

Wakalah: investment through an agent

A wakalah arrangement appoints an agent to manage an identified investment activity or pool. The important questions include what the agent may buy, how it is paid, whether the asset mix can change, and what duties it owes investors. Look through the agency label to the underlying transactions.

Other sale, manufacturing or mixed structures exist. Trading rules can also differ when certificates represent receivables rather than tangible assets or usable rights. Ask a qualified Shariah adviser to examine the specific issue; there is no universal trading rule that can safely be inferred from “sukuk” alone.

Asset-backed versus asset-based: what can you actually recover?

This is one of the most important distinctions for an investor. IFSB-7 distinguishes structures by ownership rights and recourse—the parties or assets against which investors can enforce a claim. In an asset-backed structure, asset transfer and enforceable ownership rights are central. In an asset-based structure, investors may depend substantially on obligations of the originator or another obligor, rather than being able to take possession of the referenced assets.

The terms are useful flags, not a replacement for legal analysis. Ask what “beneficial ownership” means under the governing law; whether the asset is separated from another party's insolvency; and whether the trustee can enforce the relevant agreements. A physical asset in the transaction does not automatically make it collateral pledged to certificate holders.

Read the default section before the yield section. Identify payment failures, enforcement procedures, voting thresholds, claim priority and restrictions on selling assets. If recovery relies on an undertaking from an obligor, that obligor's financial condition matters. A lawyer familiar with the relevant jurisdiction may be needed to assess enforceability. Shariah approval and legal recovery are related questions, but they are not interchangeable.

How do sukuk differ from conventional bonds?

FINRA explains conventional bonds as debt securities with terms between an issuer and investors. Compare that creditor relationship with the specific sukuk structure, rather than treating all income-paying securities as identical.

Sukuk and conventional bonds: questions that matter
QuestionSukukConventional bond
Contractual basisSpecified asset, use right or investment arrangement; documents determine rightsDebt agreement and creditor claim
Payment sourceMay involve rent, investment profits or other contractual cash flowsInterest and repayment obligations under the bond terms
Religious reviewExamine contracts, assets and the issue's Shariah opinionA conventional interest-bearing bond is not made compliant by a permissible use of proceeds
Default recoveryDepends on transfer, recourse, priority and enforceabilityDepends on seniority, security and enforceability
Possible lossDistributions can be missed; market value and capital can fallInterest or principal can be unpaid; market value can fall

The comparison does not say sukuk are safer or riskier as a group. A financially weak obligor, poor liquidity or uncertain legal rights can matter more than the category name. Assess the actual security and the price paid for it.

Are payments and principal guaranteed?

No blanket guarantee follows from the word sukuk. Distinguish a scheduled payment from a payment actually received, and an expected return from a legally enforceable obligation. If an issue uses a purchase undertaking, check who gives it, when it applies, the agreed valuation method and what happens if that party cannot perform.

Also distinguish income from total return. Receiving a distribution does not prevent the security's price from falling. An individual issue may have a maturity date, but a fund can replace maturing holdings with new issues. Unless its own documents provide otherwise, owning the fund does not create a promise to return your investment on a particular underlying security's maturity date.

What risks should a sukuk investor review?

A U.S.-filed sukuk ETF summary prospectus illustrates that these investments can face credit, market, rate, liquidity and foreign-investment risks. It is an example of risk disclosure, not a recommendation of that fund or a description of every sukuk.

  • Credit and default: A payment obligor may fail to meet its commitments. A rating is an assessment, not a payment guarantee.
  • Market-rate sensitivity: A security's market price can change when prevailing rates and required returns change, even if its contracts do not charge conventional loan interest.
  • Liquidity: A listing does not prove you can sell promptly at a fair price. Review actual dealing arrangements and exit costs.
  • Country and currency exposure: Different legal systems, political conditions and currencies can affect an investment. Check denomination and underlying exposure rather than assuming a dollar-priced fund removes every foreign risk.
  • Legal and structural risk: Asset transfers, undertakings and investor claims may be disputed or difficult to enforce.
  • Concentration and governance: Several issues may still depend on the same obligor, industry or country. Review ongoing Shariah oversight and procedures when conditions change.

Translate the risks into your own circumstances: could you need the money before the intended holding period? Could a delayed distribution interrupt essential spending? Could you tolerate selling below the purchase price? A security can satisfy a stated religious methodology yet still be unsuitable for your finances.

How can U.S. investors access sukuk?

Two broad routes are an individual issue and a pooled fund. For direct purchases, ask your brokerage whether that particular security is available to you, its minimum denomination, offering restrictions, custody arrangements and trading costs. Do not assume an international listing means unrestricted access for U.S. retail investors.

A sukuk ETF or mutual fund pools investors' money. You own fund shares, not a direct individually registered portion of each building referenced by its holdings. The fund's strategy, holdings and governance determine your exposure. Diversification can reduce dependence on one issue, but it does not eliminate loss or concentration risk.

For ETFs, the SEC's investor bulletin explains that exchange prices may be above or below net asset value. Review premiums, discounts and the bid-ask spread alongside the expense ratio. FINRA's exchange-traded product guide also emphasizes that product structures and associated costs differ. Our halal ETF evaluation guide covers the broader fund-level review.

How do you check Shariah compliance?

Obtain the issue's or fund's Shariah opinion and identify its reviewers, date, scope and methodology. Ask whether it covers the documents you will actually invest under, the asset pool and continuing operations. A recognized standard is not itself a certificate approving every security that mentions it.

AAOIFI's standards-progress page lists Standard No. 17 as under redrafting. Check the applicable issued text and the offering's opinion; do not treat a proposed change or exposure draft as a final rule. Our AAOIFI reference guide explains the difference between a standard and a provider's reviewed process.

For a sukuk fund, also ask how holdings are approved, what cash-management instruments it uses and how noncompliant income or holdings are handled. A purification process is not permission to keep an otherwise impermissible investment. NoorVest's published screening and Shariah-review documentation describes NoorVest's own process; it should not be read as approval of every sukuk issuer or fund.

What about taxes, purification and Zakat?

A religious classification does not establish U.S. tax treatment. The IRS's Publication 550 addresses investment income, fund distributions and gains or losses. Use the actual tax forms and consult a tax professional about the instrument, account type and any foreign reporting obligations. Do not assume a sukuk distribution is tax-free, necessarily a qualified dividend, or treated identically to another product.

Keep tax reporting, purification and Zakat as separate questions. If the provider reports an amount requiring purification, ask how it was calculated and obtain religious guidance. For Zakat, the treatment can depend on the investment's nature and the approach you follow. Our investment Zakat guide is a starting point for questions, not a substitute for a ruling on your holdings.

A practical sukuk due-diligence checklist

  1. Identify what you buy. Record the issue identifier or fund share class, currency, issuer, obligor and governing law.
  2. Trace ownership. Find the asset-transfer and trust provisions. Write down the actual rights—not just the brochure's description.
  3. Trace payments. Identify their source, timing, expenses and any conditions or discretion affecting distributions.
  4. Read the downside first. Note default triggers, recovery priority, trustee duties and the process for enforcement or restructuring.
  5. Check the religious review. Save the relevant opinion and ask how assets and operations are monitored.
  6. Plan your exit. Check eligibility, minimums, market liquidity, spread, settlement and custody before committing.
  7. Compare full costs. Include fund expenses, brokerage charges and any currency conversion costs; avoid comparing yields alone.
  8. Check fit and reporting. Consider cash needs, possible loss, concentration and tax responsibilities with qualified advisers.

Keep the answers beside the documents that support them. If an essential answer remains unclear, that is a reason to seek clarification, not to substitute an attractive yield or a familiar brand name.

Frequently asked questions

Are sukuk the same as conventional bonds?

No. They can have similar financing and payment features, but their contractual basis differs. Review the specific sukuk's assets, payment obligations and legal recourse rather than assuming a conventional creditor relationship.

Does every sukuk give me enforceable ownership of a physical asset?

No such conclusion follows from the label. The documents, transfer arrangements and governing law determine the investor's rights. Ask whether recovery depends on assets, an obligor's commitments, or both.

Are sukuk payments or principal guaranteed?

Not as a category. Contractual commitments may exist, but payment still depends on performance and enforceability. You can lose income or capital, and selling before an intended maturity can produce a loss.

Can a sukuk price change when interest rates move?

Yes. Changes in prevailing rates and required investment returns can affect market prices. Rate sensitivity is a market-risk question; it does not alone establish whether the underlying contract is interest-bearing.

Is a sukuk ETF the same as buying an individual issue?

No. An ETF provides fund-share exposure to its portfolio and adds fund expenses and exchange-trading considerations. Its shares do not generally mature when a particular underlying holding matures.

Does the word sukuk prove Shariah compliance?

No. Check the actual contracts, assets, Shariah opinion and ongoing oversight. A standards reference, credit rating or marketing label is not a substitute for issue-specific religious and legal review.

Putting sukuk in a financial plan

Start with the job you need an investment to do: meet a future expense, support withdrawals or diversify an existing portfolio. Then ask whether its cash flows, exit options and possible losses fit that job. NoorVest's financial planning service provides a setting for discussing those tradeoffs. If useful, request an introductory conversation. This guide does not imply that NoorVest offers every sukuk, acts as an arranger, or recommends a particular issue or fund.

Important disclosure

This article is educational and may be considered an advertisement for NoorVest. It is not personalized investment, legal or tax advice, a religious ruling, or an offer to buy or sell securities. Investments can lose value; past performance does not guarantee future results. Product availability, contracts and standards can change. Consult qualified Shariah, investment, legal and tax professionals as appropriate to your circumstances.

About the author

Tarif Homsi is NoorVest's founder and CEO. His work focuses on financial planning and halal wealth management for U.S. Muslim investors. Sources reviewed October 1, 2026.

Primary sources and further reading

Get Free Consultation
Light Mode
Toggle cloudsstars