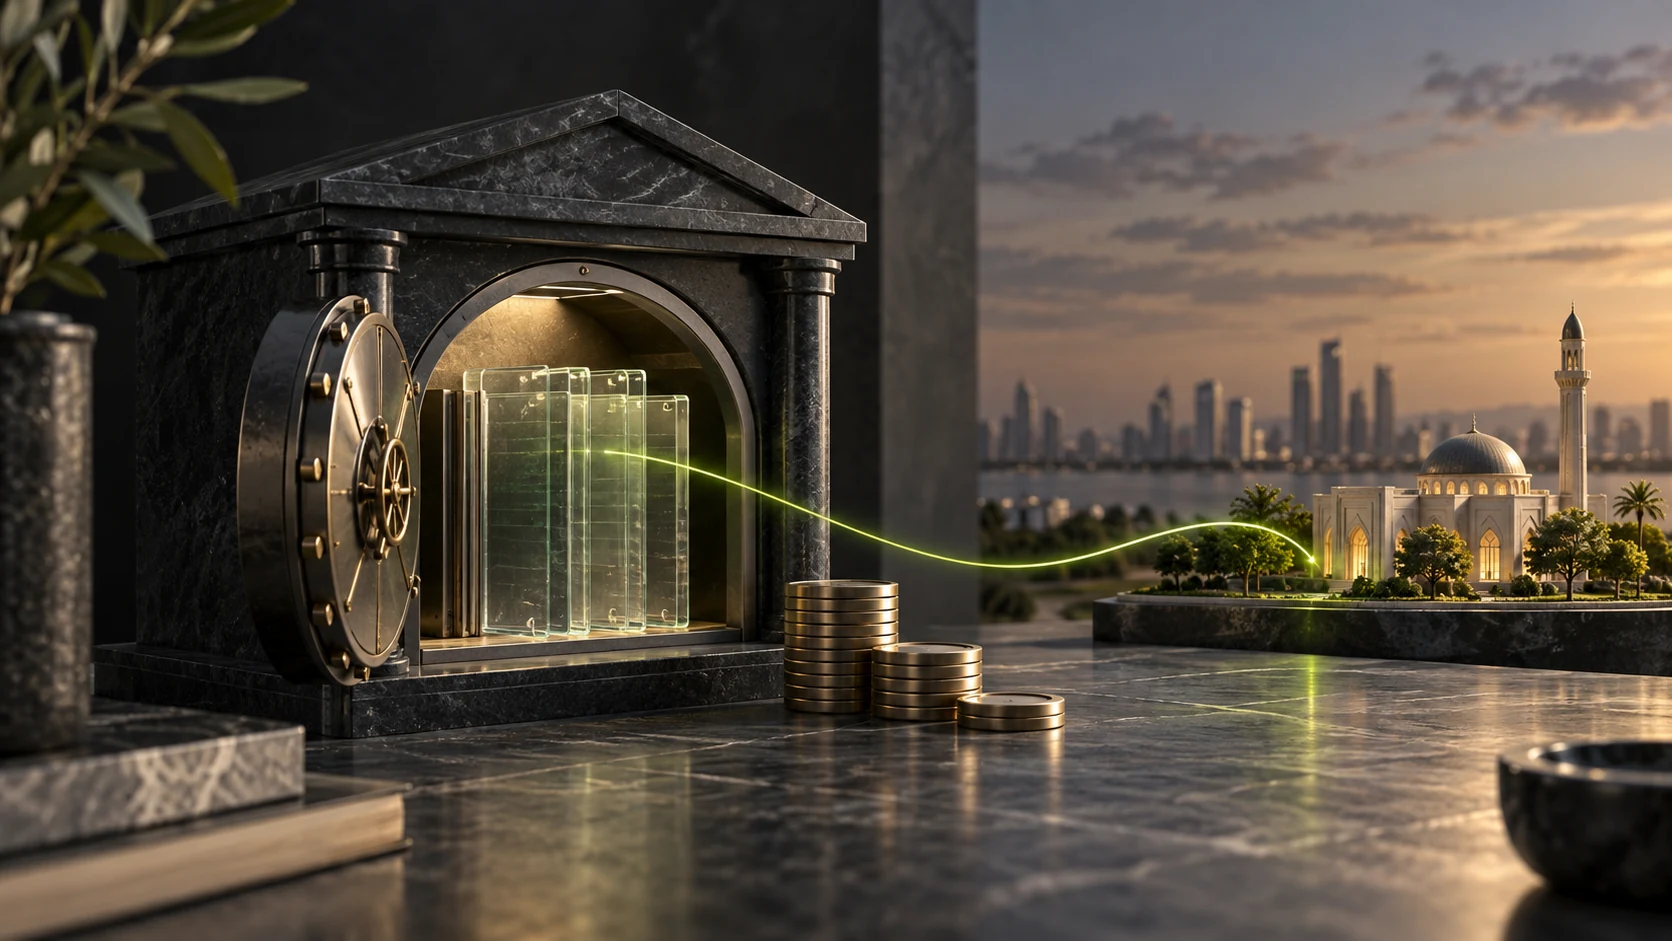
Dark stone vault with translucent savings-account ledgers and a green line linking the account to a community building.
Blog

Halal Savings Accounts in the USA: What to Check Before You Open One

A practical guide to halal savings accounts in the United States, covering profit-sharing structures, FDIC protection, fees, access to cash, taxes, and Shariah oversight.
September 25, 2026
1-Min Summary

By Tarif Homsi, Founder & CEO

Short answer: A halal savings account is a cash account whose terms have been structured and reviewed to avoid conventional interest. Some U.S. providers offer profit-sharing deposit accounts. Others offer noninterest accounts that simply hold cash. These are not interchangeable, and a product's name does not tell you who holds the money, how any return is generated, or what protections apply.

For a U.S. saver, the first questions are practical: Is this a deposit at an FDIC-insured bank? Is the return interest, an anticipated share of profit, or no return at all? Can you withdraw when you need to? Who reviewed the Shariah structure, and what exactly did that review cover? This guide helps you read those answers before opening an account. It does not rank providers or offer a religious ruling.

  • A conventional savings account generally pays interest; a Shariah-reviewed profit-sharing account uses a different contract.
  • FDIC insurance addresses eligible deposits at an insured bank, not whether an account is halal or whether a projected profit will be paid.
  • Check fees, withdrawal rules, sweep arrangements and current disclosures alongside the Shariah opinion.

What makes a savings account halal?

The contract matters more than the label. A conventional savings account commonly pays interest on a deposit. A provider marketing a halal savings account should be able to explain a different arrangement, such as an agency or profit-sharing structure, and show how the deposited money is used. The review should cover the actual terms, not just a general statement about Islamic finance.

That does not mean every account with no advertised interest has received a Shariah review. A noninterest checking account may meet a person's immediate cash-access need, but its overdraft terms, automatic sweep, linked products and other features still deserve attention. Nor does an anticipated profit figure mean the same thing as a fixed, guaranteed payment. Read the account agreement and the Shariah documentation together.

AAOIFI Shariah Standard No. 40 addresses the distribution of profit in mudarabah-based investment accounts and distinguishes those from current accounts. It is one relevant reference, not a declaration that every U.S. product follows the same contract. A qualified Shariah adviser can assess a specific account's documents under the standard you follow.

How is a profit-sharing account different from ordinary savings?

In a conventional account, the bank's promise to pay interest is the central return feature. A Shariah-reviewed profit-sharing account aims to connect the depositor's return to permissible activity under a specified contract. The provider may use terms such as mudarabah or wakalah. The exact allocation of profit, fees, agency duties, loss treatment and payment timing depends on the documents. Do not assume the same mechanics apply across providers simply because both advertise a “halal” account.

The difference between an anticipated return and a contractual guarantee is especially important. Ask what the provider estimates, what it legally promises, when profits are calculated, and what could reduce or delay a payment. Read any disclosure about reserve accounts, smoothing practices or changes to the expected rate. An attractive number on a page is not the contract.

Cash products that may appear similar but require different checks
ProductWhat it generally doesFirst question to ask
Conventional savings accountHolds bank deposits and ordinarily pays interestWhat are the interest, fees and withdrawal terms?
Shariah-reviewed profit-sharing savingsHolds eligible deposits under a documented alternative return structureWhat is the contract, source of profit and scope of Shariah review?
Noninterest checkingProvides transaction access without an advertised returnAre there overdraft, sweep or linked interest features?
Money market mutual fund or sukuk fundInvests in securities rather than functioning as a bank depositWhat can the fund hold, lose, charge or restrict?

A fund should not be described as a savings account just because its price has usually moved less than stock prices. The FDIC lists deposit products it insures and separately identifies mutual funds and securities it does not insure. Our halal ETF guide explains the investment side of that distinction.

Are halal savings accounts available in the United States?

Yes, but the market is narrower than an online search for “Islamic savings” might suggest. Many search results describe products available only in the United Kingdom, Gulf states or other countries. U.S. readers should confirm that a provider accepts customers in their state, identify the actual deposit-taking bank, and read current U.S. account disclosures.

Two examples checked against provider websites on September 23, 2026 illustrate different presentations. UIF describes a profit-sharing savings account offered through University Bank, Member FDIC. UIF says it acts as an agent and that its Shariah Supervisory Board reviews the arrangements. Stearns Salaam Banking, a division of Stearns Bank N.A., describes savings and other Islamic banking products reviewed by its Sharia Supervisory Board. These mentions are examples, not a comparison, endorsement, or statement that either account suits a particular reader.

Features, eligibility, bank relationships and documents can change. Verify them with the provider before applying. In particular, do not rely on an undated list of “best” halal accounts or assume that a foreign product is available to U.S. residents.

What does FDIC insurance cover?

For an eligible deposit at an FDIC-insured bank, the standard insurance amount is $250,000 per depositor, per insured bank, for each ownership category, under the FDIC's rules. The FDIC covers specified deposits if an insured bank fails. It does not insure stocks, mutual funds or other securities, and it does not make a judgment about Shariah compliance. Read the FDIC's deposit insurance guide for the ownership categories and aggregation rules.

If you open an account through a company that is not itself a bank, ask which bank holds the funds and in whose name. Pass-through coverage can apply to money held through an intermediary when specific ownership and recordkeeping conditions are met. It is not a separate $250,000 limit, and balances at the same bank in the same ownership category may be combined. “Our banking partner is FDIC insured” is a starting point, not enough to determine coverage for your own balances.

Deposit insurance also does not guarantee a particular expected profit or protect against losses in a separate investment product. Keep those questions separate: legal deposit protection, contractual return, and Shariah assessment answer different concerns.

What should you read before opening an account?

Begin with the current account agreement and fee schedule. The Consumer Financial Protection Bureau's Truth in Savings rules set disclosure requirements for covered deposit accounts, including information consumers use to compare terms. An expected annual percentage yield, when shown, is not a substitute for understanding how a Shariah-reviewed profit is earned or allocated.

Access to your cash

An emergency fund has a job: it must be there when an expense arrives. Ask how long transfers take, whether debit or ATM access exists, and whether withdrawals are limited. The CFPB notes that banks can set withdrawal limits or charge fees for excessive transfers and minimum-balance shortfalls. A time-deposit product may impose a different commitment or early-withdrawal consequence from an ordinary savings account.

Every fee and linked feature

Read the monthly fee, opening deposit, balance requirements, transfer charges and account-closing terms. Check whether an overdraft service, debit feature or automatic cash sweep adds a separate agreement. If the provider advertises a profit figure, ask whether fees are deducted before or after it is calculated. The answer should be in the documents, not inferred from a headline rate.

Shariah oversight

Look for the names of the reviewing scholars or board, the date of their opinion, the products covered, and how ongoing use of deposits is monitored. Ask whether the review covers a savings account, time deposit, checking account or all three. An institution's membership in a standards organization, use of an Arabic contract name, or “ethical” branding is not direct certification of every account it offers. NoorVest's AAOIFI explainer distinguishes standards, aligned methodologies and product-specific reviews.

What about a high-yield savings account?

“High-yield” describes a rate relative to other deposit accounts. It does not describe the legal source of the return or supply a Shariah opinion. Many conventional high-yield savings accounts pay interest. A profit-sharing account could also display an expected yield for comparison, but its governing contract needs separate review. Compare the account's substance before comparing the size of its quoted return.

For money needed soon, the trade-off between access, deposit protection, contract structure and return matters more than a single advertised number. For money intended for long-term growth, an investment account may serve a different purpose, with different risks and no FDIC protection for securities. NoorVest's financial planning work considers liquidity alongside longer-term investing rather than treating every dollar of cash as a portfolio holding.

How are account earnings taxed?

Do not infer U.S. tax treatment from a Shariah label. The tax characterization of payments depends on the actual arrangement and reporting. The IRS explains in Publication 550 how interest on bank deposits is generally reported and distinguishes other investment income. A provider may issue tax forms for an account's earnings; ask which forms you should expect and keep the provider's statements. A qualified tax professional can review an unusual profit-sharing arrangement in your circumstances.

Religious purification and U.S. taxation are separate matters. Giving away an amount for Shariah reasons does not automatically erase a reporting obligation or create a deductible charitable gift. Likewise, choosing a noninterest account does not mean the account has no tax or recordkeeping implications. Avoid making a tax decision from a general blog example.

A practical account-opening checklist

  1. Identify the legal provider. Who takes the deposit, and is that institution FDIC insured? If an intermediary is involved, ask how your ownership is recorded.
  2. Read the contract. Is the account noninterest, profit-sharing, agency-based or another structure? What is promised, and what is merely anticipated?
  3. Verify the review. Find the named Shariah board, its product-specific opinion and the process for monitoring the account after launch.
  4. Check how money is used. Ask about eligible assets, segregation, sweeps and the source of any return.
  5. Test access. Confirm transfer time, withdrawal limits, minimums, fees, and what happens when you need funds unexpectedly.
  6. Calculate your deposit coverage. Include other balances you already hold at the same bank and ownership category; use the FDIC's rules rather than assuming a fresh limit for each app.
  7. Review tax reporting. Ask what forms may be issued and seek professional advice when the account structure is unfamiliar.
  8. Recheck the terms. Products, expected returns and bank partnerships change. Save the version of the documents you accepted and review later updates.

None of these steps is a personal recommendation to open a particular account. They give you a way to compare documents and ask better questions.

Frequently asked questions

Is a regular savings account halal if I leave the interest untouched?

That is a religious question about a specific account and your circumstances. Leaving interest in an account does not change the contract that generates it. Ask a qualified Shariah scholar about the arrangement and how any interest already received should be handled.

Is a noninterest checking account the same as a halal savings account?

No. A checking account is built for payments and may pay no return. A savings account is built for holding funds and may have different access rules. Review overdraft, sweep, fees and any linked product even when the headline account pays no interest.

Does FDIC insurance mean a bank account is Shariah-compliant?

No. FDIC insurance concerns eligible deposits if an insured bank fails, subject to coverage rules. Shariah compliance concerns the account's contract, use of funds and oversight. Neither assessment replaces the other.

Is an expected profit rate guaranteed?

Do not treat “expected” as a guarantee. Read the provider's agreement to see how profit is generated and allocated, what can change, and what is legally promised. Deposit insurance, where applicable, does not guarantee an advertised expected profit.

Can I use a sukuk fund instead of an emergency savings account?

A sukuk fund is an investment, not a bank deposit. Its value can move, withdrawals can depend on fund mechanics, and its shares are not FDIC insured. Whether it belongs in a personal plan depends on liquidity needs and risk tolerance, not just its Shariah label.

Does NoorVest offer a savings account?

No. NoorVest is an investment adviser, not a bank or deposit-taking institution. It can discuss how cash needs and halal investing fit within a financial plan, but the accounts mentioned in this guide are offered by their own providers.

Where NoorVest fits

A cash reserve and a long-term investment portfolio serve different purposes. NoorVest helps clients think through liquidity and financial planning alongside Shariah-conscious investing. Its published certification and screening process concerns NoorVest's own platform; it does not certify the third-party deposit accounts discussed here. If you want to discuss the planning side, you can request an introductory conversation.

Important disclosure

This article is educational and may be considered an advertisement for NoorVest's advisory services. It is not a fatwa, Shariah certification of a named account, individualized investment, banking, legal or tax advice, or an endorsement of a third-party provider. NoorVest does not offer deposit accounts. Product terms, eligibility, expected returns, bank relationships and Shariah opinions can change. Deposit insurance is subject to FDIC rules; securities can lose principal and are not FDIC insured. Review current provider documents and consult qualified professionals as appropriate.

Written by Tarif Homsi. Product examples and sources checked September 23, 2026.

Primary sources and further reading

Get Free Consultation
Light Mode
Toggle cloudsstars